Identify the disputed cause
Separate the damage attributed to wind, hail, water entry or flooding. Ask your insurer which policy terms it relied on for each part of the decision.
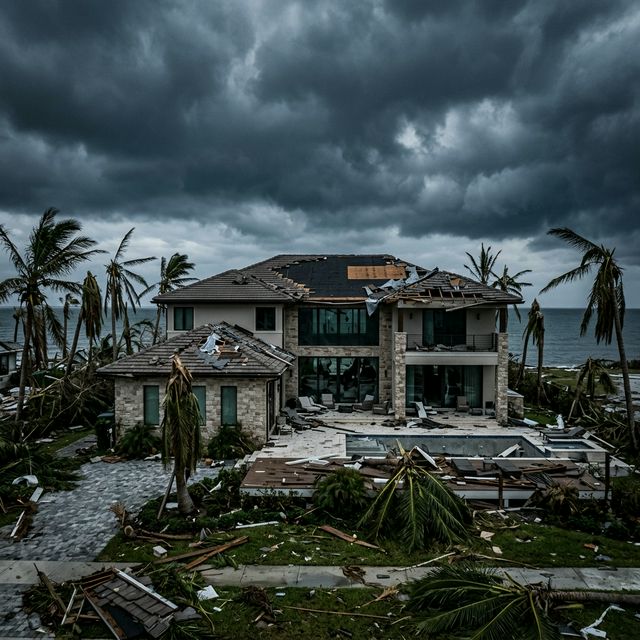
Fayetteville properties face severe storms, hurricane remnants, and hail. We help organize damage records and review a denial or partial payment against the policy and available evidence. Coverage and any recovery depend on your claim.
Claim Guardians works for homeowners and business owners in Cumberland County. We review the policy, document property damage and communicate with the insurer within the agreed scope of representation.
Confirm the assigned professional’s current state credentials before signing. Service-area coverage does not imply a branch office in every city.
Share your contact details and a short summary. There is no need to have every document ready to request a conversation.
Insurance companies operating in Cumberland County know these risks — and they train their adjusters to minimize what they pay you. Here's what we fight for.
Fayetteville's position in the Carolina Sandhills means it receives significant impact from Atlantic hurricanes moving inland. Hurricanes Florence (2018), Matthew (2016), and Helene (2024) all caused major damage in Cumberland County. Insurance companies delay and underpay military community claims knowing frequent relocations make follow-up harder.
Learn about our storm claim process →Severe thunderstorms bringing large hail and damaging winds are common from spring through fall. Cumberland County's mix of older military housing and newer developments creates complex damage assessments that insurance adjusters often undervalue.
Learn about our water damage process →The Cape Fear River basin makes low-lying Fayetteville neighborhoods vulnerable to flooding during major rain events. Insurance carriers dispute whether damage is from covered 'wind-driven rain' or excluded 'rising water.'
Learn about denied claim appeals →Pipe bursts, hidden moisture, flood
Wind, hail, tropical storm impact
Structural failures, hail hits, leaks
Structural loss and smoke assessment
Post-water exposure documentation
Appeals and forced full payment
Our NC-licensed adjusters visit your Fayetteville property and document all damage — including what insurance adjusters miss. This costs you nothing.
We prepare a comprehensive claim, file all paperwork, and negotiate directly with your insurer. You don't deal with adjusters, calls, or paperwork.
Settlement check in your hands. We collect our fee only after you get paid. If we don't recover anything, you owe us nothing.
Looking for help at another property? Choose its city or view our statewide coverage.
Start with the damage you can document and the decision you need explained. We review the policy and available records, identify missing information and discuss whether representation fits your situation.
Separate the damage attributed to wind, hail, water entry or flooding. Ask your insurer which policy terms it relied on for each part of the decision.
Bring the denial letter and insurer’s estimate. Match each disputed finding with photographs, inspection notes or a contractor’s explanation.
A previous denial or payment does not establish whether a claim can be changed. The policy, loss date, prior communications and applicable deadlines need review.
Enter only a short summary in the form. Keep policy numbers, financial records and private documents for the follow-up conversation.
The initial review does not guarantee coverage or a settlement. Confirm the assigned professional’s credentials and proposed terms before engagement.
Official consumer resources
North Carolina DOI: homeowners insurance and consumer assistanceResources checked October 19, 2026. Coverage and deadlines need review for your particular policy and loss.
Our field adjusters respond to claims in Fayetteville and surrounding areas including Fort Liberty (Bragg), Spring Lake, Hope Mills, Sanford, Lumberton, and all of Cumberland County.
Bring your policy, dated photos, repair estimates or reports, and any insurer letters. If the claim was denied or paid, include the decision and a timeline of communication. The review considers your policy and documented damage; it does not guarantee coverage or a particular settlement.